The Federal Reserve just hiked rates for the first time since 2023 as it tries to tamp down persistently high inflation. Inflation is currently running above 3%, higher than the Fed’s 2% target. That has most Fed watchers expecting further rate hikes.
Higher rates are a headwind for high-yield dividend stocks. At over 10%, Ares Capital (ARCC +0.37%) is certainly in that category, given that the S&P 500‘s dividend yield is closer to 1%. Despite that, I’d still buy Ares Capital right now.

Image source: Getty Images.
Why high rates are headwinds for high-yielding stocks
The Fed recently raised the Federal Funds Rate by 25 basis points, moving it from 3.50%-3.75% to 3.75%-4.00%. New York Fed President John Williams has since said that another rate hike this year is a “reasonable expectation.” The market is currently pricing in a 25-basis-point increase at the Fed’s October meeting, with an even higher probability of a hike at its December meeting.
Rising interest rates have two notable impacts on high-yielding dividend stocks. It increases their borrowing rates. Interest rates on floating-rate debt rise, while it’s more expensive to issue new debt to refinance existing borrowing or fund new investments. Higher interest rates will directly impact Ares Capital’s balance sheet because $11.8 billion of its $15.9 billion in outstanding debt (74%) was floating-rate at the end of the second quarter. On a positive note, the business development company (BDC) just raised $750 million in notes due in 2033 at a fixed 6.25% rate just before the Fed raised rates, providing it with additional capital.

Today’s Change
Current Price
The other impact of rising rates is that it makes lower-risk income investments such as government bonds and bank CDs more attractive. That weighs on the value of riskier income investments like high-yield dividend stocks, pushing up their yields to compensate investors for their higher risk profiles. We’ve seen that with Ares Capital this year as shares are down nearly 10% from their high, pushing its yield above 10%.
Why I’d still buy Ares despite these headwinds
While Ares Capital has some headwinds from higher rates, they’re also a tailwind. At the end of the second quarter, 71% of Ares’ $29.3 billion investment portfolio was in floating-rate debt. That means rising rates will boost the interest income generated from those holdings, more than offsetting the increased interest expenses on its debt. The company has focused on investing in floating-rate debt in recent quarters. Of its $2.6 billion of new investment commitments in the second quarter, 94% was floating rate debt securities.
Ares Capital also has an exceptional record of investing during periods of rising interest rates. The clearest evidence of this is its 17-year record of paying a stable-to-growing regular dividend, which includes several periods of interest rate hikes. Its total dividend outlay (regular and supplemental) has historically risen during periods when the Federal Reserve is increasing rates:
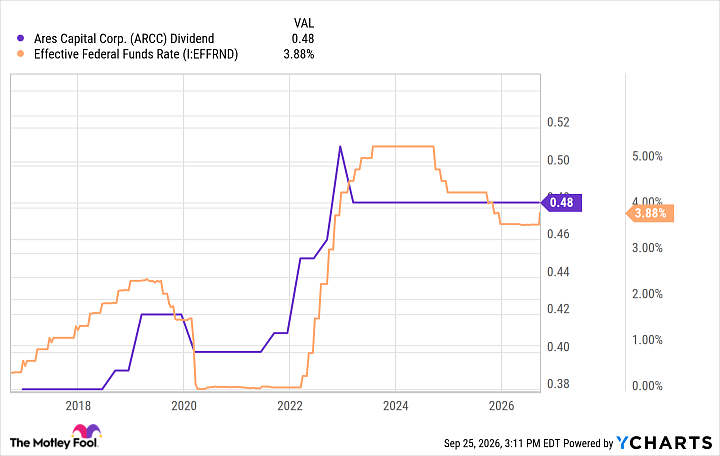
ARCC Dividend data by YCharts
I’d capitalize on the rate-driven decline
Rising rates will likely continue to put downward pressure on Ares stock price, driving up its yield. I think that will make an already solid buying opportunity even better. While there’s no guarantee that Ares Capital will maintain its record of dividend stability and growth during the current rate hike cycle, it’s in a strong position to capitalize on higher rates, as it has in the past.