Tapestry’s stock price has taken a beating over the past six months, shedding 22.4% of its value and falling to $112.14 per share. This might have investors contemplating their next move.
Is there a buying opportunity in Tapestry, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think Tapestry Will Underperform?
Despite the more favorable entry price, we don’t have much confidence in Tapestry. Here are three reasons we avoid TPR, plus one stock we’d rather own.
1. Weak Constant Currency Growth Points to Soft Demand
In addition to reported revenue, constant currency revenue is a useful data point for analyzing Consumer Discretionary – Apparel and Accessories companies. This metric excludes currency movements, which are outside of Tapestry’s control and are not indicative of underlying demand.
Over the last two years, Tapestry’s constant currency revenue averaged 10.1% year-on-year growth. This performance was underwhelming and suggests it might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 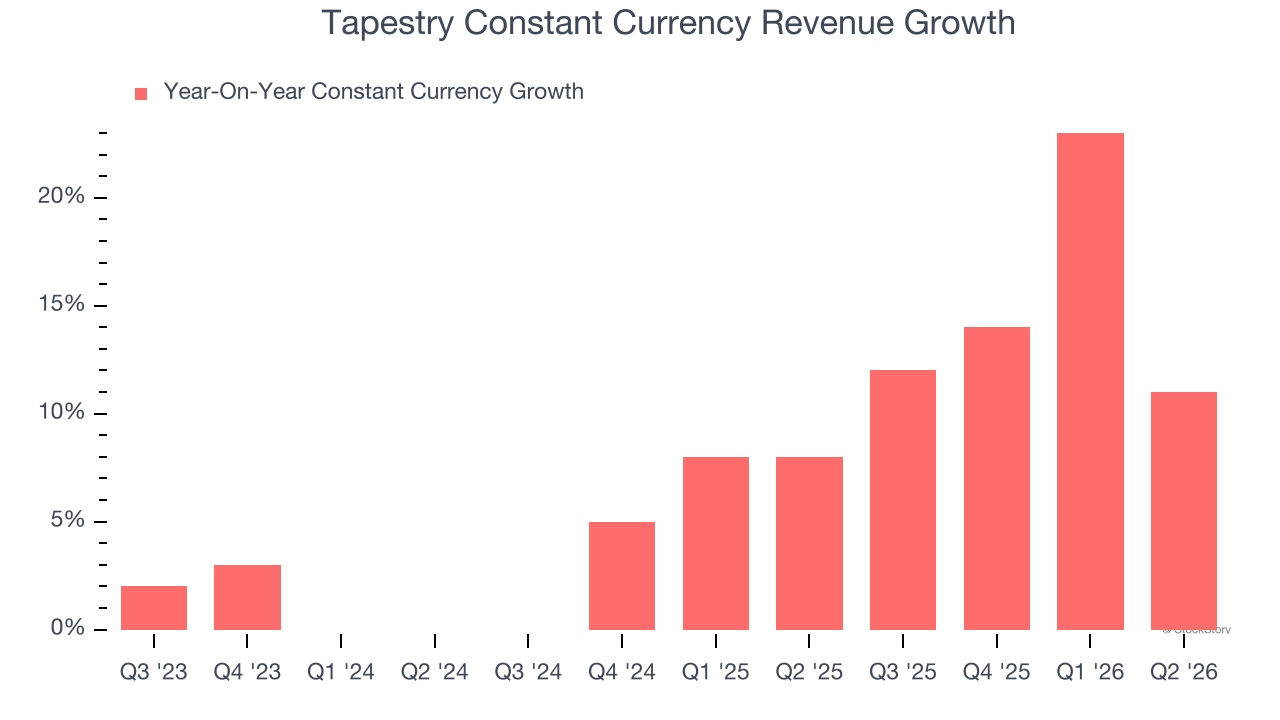
2. Cash Flow Margin Set to Decline
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Over the next year, analysts predict Tapestry’s cash conversion will fall. Their consensus estimates imply its free cash flow margin of 22.7% for the last 12 months will decrease to 19.4%.
3. New Investments Fail to Bear Fruit as ROIC Declines
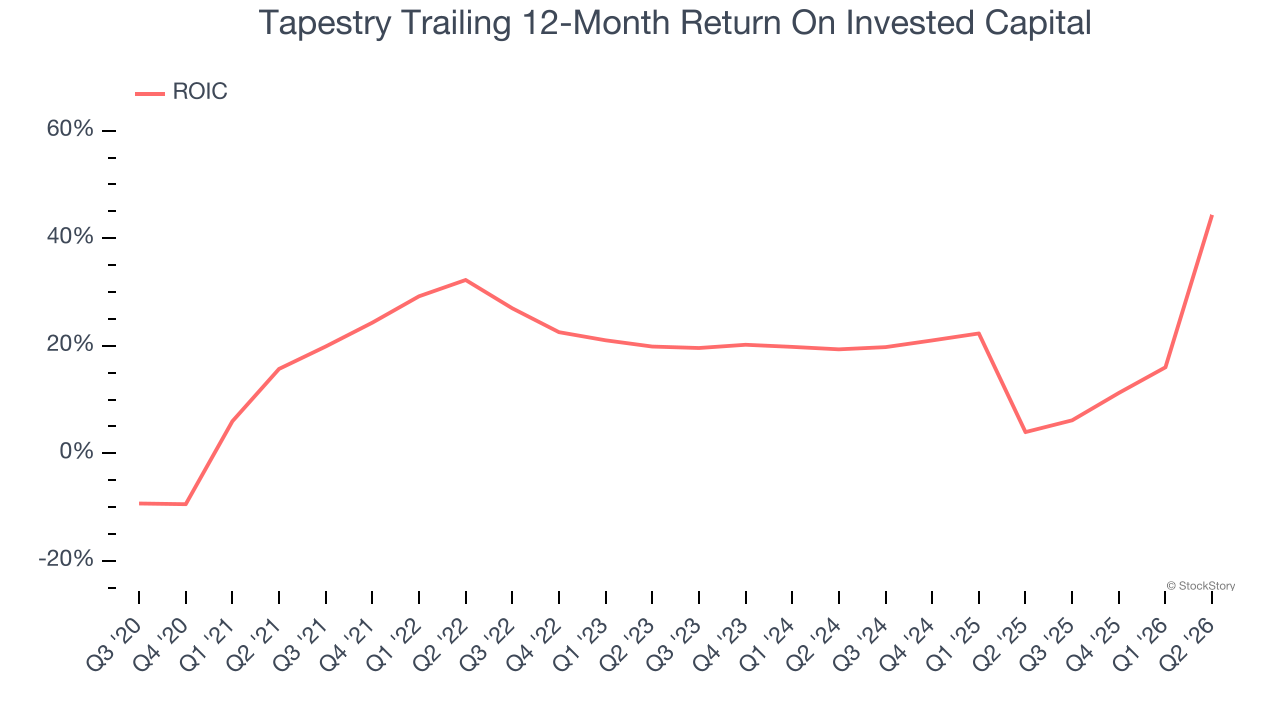
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
On average, Tapestry’s ROIC decreased by 1.9 percentage points annually each year over the last few years. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
Final Judgment
We see the value of companies helping consumers, but in the case of Tapestry, we’re out. After the recent drawdown, the stock trades at 14.2× forward P/E (or $112.14 per share). This multiple tells us a lot of good news is priced in – we think other companies feature superior fundamentals at the moment. We’d recommend looking at one of our top software and edge computing picks.
Stocks We Like More Than Tapestry
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.