-
The analyst said that while revenue guidance and backlog growth look promising, the firm sees “share prices as heavily weighted on optimistic expectations.”
-
The analyst said it was maintaining its ‘Extreme Uncertainty Rating’ on BE stock, with a $102 price target, implying a downside of more than 47% from its last close.
-
BE posted its third-quarter results last week, beating Wall Street expectations on both the top and bottom lines, although negative cash flows weighed heavily on investor sentiment.
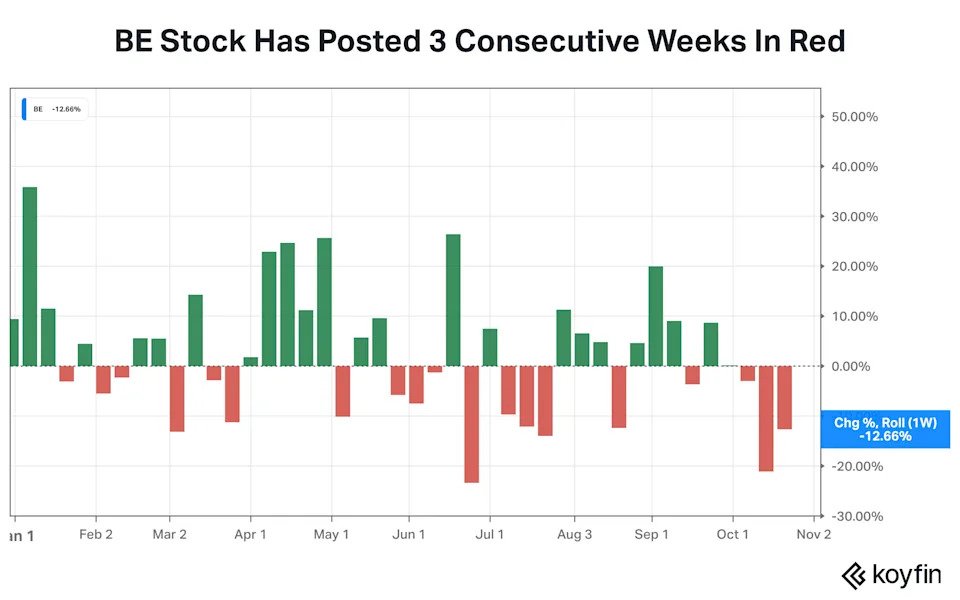
Bloom Energy Corp. (BE) shares were down nearly 2% in overnight trading late Sunday after three consecutive weeks in the red following its latest quarterly print.
Meanwhile, Morningstar said in a note on Friday that it is reviewing BE shares as it reassesses its long-term thesis. The analyst said that while revenue guidance and backlog growth look promising, the firm sees “share prices as heavily weighted on optimistic expectations.”
BE posted its third-quarter results last week, beating Wall Street expectations on both the top and bottom lines, although negative cash flows weighed heavily on investor sentiment.
Morningstar Maintains ‘Extreme Uncertainty Rating’ On BE Stock
The analyst said that it was maintaining its ‘Extreme Uncertainty Rating’ on BE stock, with a price target of $102, implying a downside of more than 47% from its last close.
Morningstar said questions about Bloom’s supply chain, backlog, and working capital management have remained “unanswered,” and management’s lack of clarity on market concerns “hurts” the stock.
“We expect to remain at the lower end of valuations as we believe this stock is, at worst, priced with extreme optimism and, at best, priced to perfection,” it said.
What Are Other Analysts Saying About BE Stock?
Last week, Jefferies analyst Julien Dumoulin-Smith lowered Bloom Energy’s price target to $242 from $289 and kept a ‘Hold’ rating on the shares.
The analyst said that despite another 2026 guidance raise and management’s comments that backlog continues to outpace revenue growth, Bloom did not provide a formal backlog update. Meanwhile, the highlighted recent wins were “already well known” and the company did not address delays related to its largest opportunity at Oracle’s (ORCL) Project Jupiter, it said.
BTIG also lowered its price target on Bloom Energy to $250 from $295 and maintained a ‘Buy’ rating after its Q3 results. The firm said management cited near-term margin pressure from ramping up new production capacity and expedited customer timelines, adding that the company remains in a prime position to deliver much-needed BtM generation capacity. However, the cost of adding manufacturing capacity is weighing on the margin story, the firm said.