- Atlantic Union Bankshares recently received an analyst upgrade to a Zacks Rank #2 rating after earnings estimates were revised upward, signaling increased confidence in its profit outlook and core banking performance.
- The improved earnings view highlights how Atlantic Union Bankshares’ mix of Southeast market exposure, digital investment, and business banking focus is shaping expectations for its long-term profitability profile.
- We will now explore how Atlantic Union Bankshares’ broader investment narrative could be affected by the stronger earnings outlook highlighted in this upgrade.
Position your portfolio to capture the type of earnings momentum behind Atlantic Union Bankshares’ upgrade by scanning a curated 30 high quality undervalued stocks featuring companies with resilient balance sheets and solid cash generation.
Atlantic Union Bankshares Investment Narrative Recap
To own Atlantic Union Bankshares, you need to be comfortable with a fairly traditional regional bank that leans on Southeast growth, business banking relationships, and ongoing branch expansion in places like North Carolina. The recent uplift in earnings estimates supports that operating story but does not change the core thesis that execution on loan quality, deposits, and integration still matters most.
The key near term swing factor remains margin and funding pressure as competition for deposits stays intense. The biggest risk is that higher operating costs from expansion and M&A integration, together with any adverse regional shock, squeeze profitability more than expected. The estimate upgrades do not fully remove that concern.
The recent upgrade tied to higher earnings projections effectively highlights work already under way at Atlantic Union Bankshares. Management has been integrating acquisitions such as Sandy Spring Bank and American National while reshaping the balance sheet, including a sale of commercial real estate loans that aimed to reduce concentration and free capacity.
Those moves align closely with today’s main catalysts. Cleaner commercial real estate exposure, deeper customer relationships, and investment in digital banking all contribute to the earnings trajectory analysts are now revising. The same actions carry execution risk, particularly around integration costs and technology delivery, which is where any future disappointment would likely show up first.
Atlantic Union Bankshares’ story is anchored to analyst projections that call for about US$1.8b in revenue and US$647.2 million in earnings by 2029. That profile reflects assumed yearly top line growth of 5.2% and an earnings step up of roughly US$171.8 million from the current US$475.4 million level.
Uncover why Atlantic Union Bankshares’ fair value indicates a 22% potential upside to its current price, which could narrow quickly.
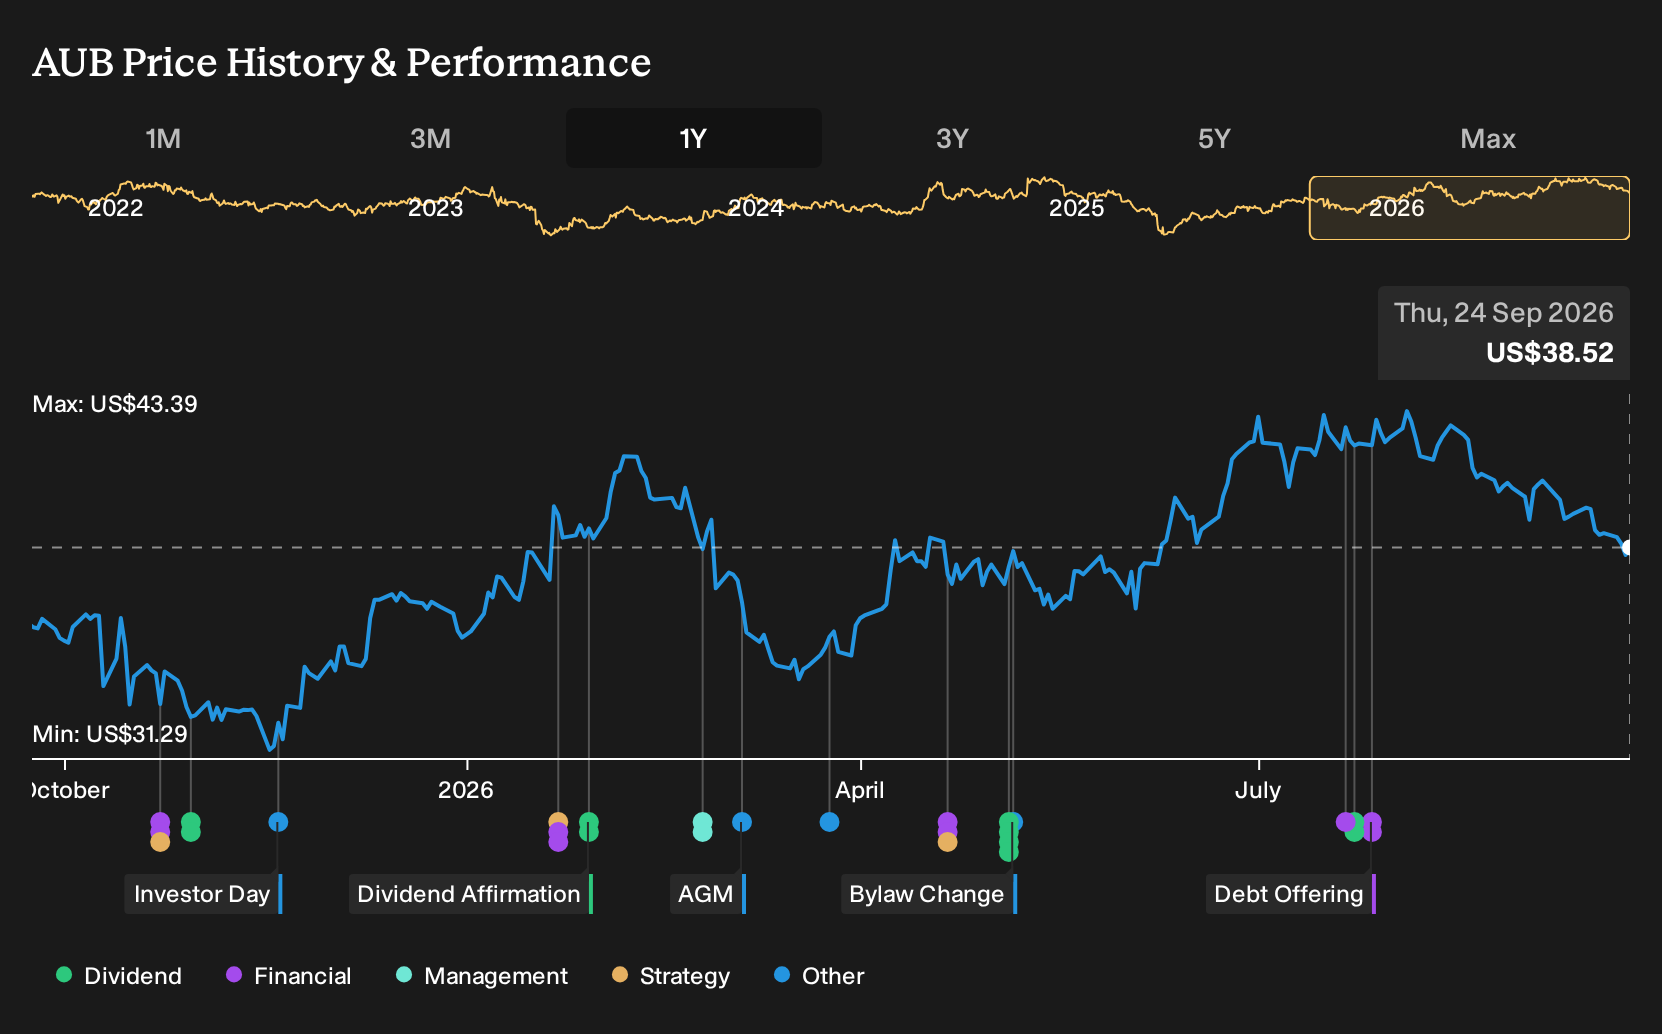
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$47 to about US$63.37, so retail opinions on Atlantic Union Bankshares already stretch across more than US$16 per share. That spread sits beside real risks around regional concentration and M&A integration, which you should weigh before you explore more of these contrasting viewpoints.
Explore 2 other Atlantic Union Bankshares fair value estimates, including one that suggests there may be as much as 65% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Atlantic Union Bankshares research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Atlantic Union Bankshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atlantic Union Bankshares’ overall financial health at a glance.
Looking For More Investment Ideas Beyond Atlantic Union Bankshares?
If Atlantic Union Bankshares has sharpened your focus on earnings quality, balance sheet strength, and long term return potential, it can be useful to widen the lens and scan for other businesses that line up with your preferred risk and income profile using the Simply Wall St Screener.
- For resilient businesses where downside risk is a key concern, review a 30 resilient stocks with low risk scores that already score well on financial strength and volatility.
- If dependable income is higher on your priority list, scan a curated 7 dividend fortresses that focus on higher yielding payouts with supporting fundamentals.
- When you want ideas that combine solid accounts with room for the market to catch up, run through a 16 high quality undiscovered gems that surface quality companies still flying under most investors’ radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com