Khac Phu Nguyen
This article first appeared on GuruFocus.
Micron Technology, the memory and storage-chip producer (NASDAQ:MU), faces tougher questions about the durability of its memory boom, with shares at $898.77, down 3.5%, around 10:34 a.m. ET on October 16. According to Benzinga, Bernstein analyst Mark Newman sees value in memory stocks after their retreat, even as price increases lose momentum. Slower increases do not mean prices are falling. They do put more pressure on earnings growth to justify the investment story.

Micron’s September 30 earnings release reported quarterly revenue of $54.229 billion and adjusted free cash flow of $33.199 billion. That is roughly 61.2 cents of adjusted free cash flow for every revenue dollar. Management’s next-quarter sales forecast stands at $61.5 billion, plus or minus $1.5 billion. The midpoint implies another 13.4% sequential increase. Cash gives Micron room to expand. Earning attractive returns on that expansion is the next test.

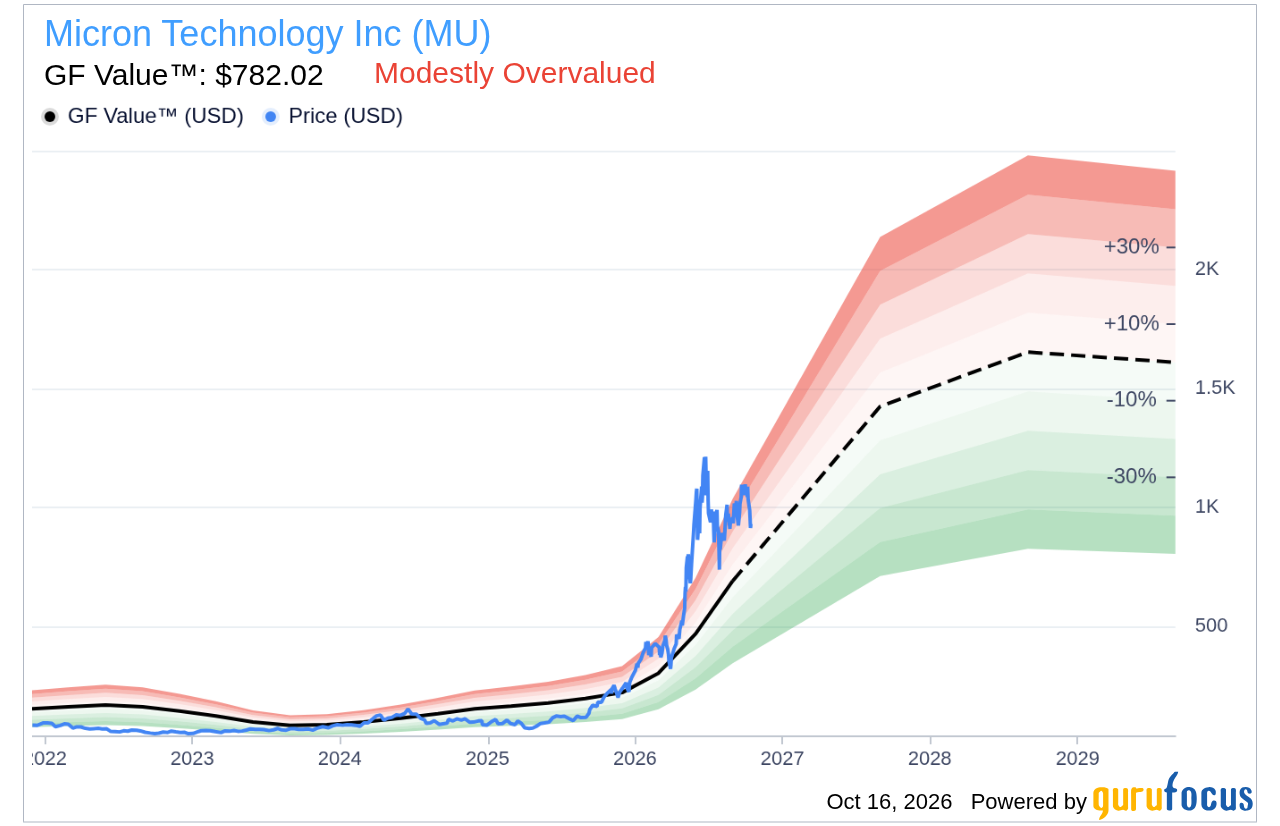
The valuation snapshot shows shares trading 14.63% above GF Value of $784.03, suggesting the pullback has not erased the premium to that estimate. Investors still need to weigh that premium against future growth. The Stock Analysis overview provides additional financial context, but the operating numbers deserve the closest watch: revenue, margins and capital spending. Strong cash generation can fund more production. Sustained demand and disciplined spending will determine whether that production creates lasting shareholder value.